
Last updated: November 2026. Federal income tax only; excludes Social Security/Medicare (FICA), state tax, credits and itemized deductions.
“How much should I pay in federal income tax?” and “what’s the federal tax on $80,000 married filing jointly?” are two of the most common tax questions online – and the answer is almost always less than people expect, because the U.S. uses marginal brackets. This guide lays out the official 2026 federal tax brackets, walks through a full worked example, and shows how to use a tax bracket calculator to estimate your own bill.
Prefer to skip the math? Use our tax bracket calculator or the federal income tax calculator for a personalized estimate.
- 2026 standard deduction: $16,100 (single), $32,200 (married filing jointly), $24,150 (head of household).
- Only the income within each bracket is taxed at that bracket’s rate – moving into a higher bracket never reduces your take-home pay.
- A married couple earning $80,000 in wages owes about $5,240 in federal income tax – an effective rate of 6.6%.
- These are the brackets for income earned in 2026, which you’ll file in early 2027.
- 2026 federal income tax brackets
- How marginal tax brackets actually work
- Federal tax on $80,000 married filing jointly (2026 example)
- Estimated federal income tax at common incomes
- Head of household vs. single: what’s the difference?
- Why you get a refund (or owe)
- 5 ways to lower your federal income tax bill
- Worked example: $60,000 single filer
- Will a raise push you into a higher bracket and cost you money?
- Deduction vs. credit: they are not the same
- Federal income tax vs. payroll taxes (FICA)
- How to estimate your 2026 federal income tax in 5 steps
- 6 common tax-bracket mistakes
- Frequently asked questions
2026 federal income tax brackets
The IRS announced the 2026 inflation adjustments in Revenue Procedure 2025-32. Here are the taxable-income ranges for the three most common filing statuses (summarized by the Tax Foundation):
| Rate | Single | Married filing jointly | Head of household |
|---|---|---|---|
| 10% | $0 – $12,400 | $0 – $24,800 | $0 – $17,700 |
| 12% | $12,401 – $50,400 | $24,801 – $100,800 | $17,701 – $67,450 |
| 22% | $50,401 – $105,700 | $100,801 – $211,400 | $67,451 – $105,700 |
| 24% | $105,701 – $201,775 | $211,401 – $403,550 | $105,701 – $201,750 |
| 32% | $201,776 – $256,225 | $403,551 – $512,450 | $201,751 – $256,200 |
| 35% | $256,226 – $640,600 | $512,451 – $768,700 | $256,201 – $640,600 |
| 37% | $640,601+ | $768,701+ | $640,601+ |
2026 standard deduction
| Filing status | Standard deduction |
|---|---|
| Single | $16,100 |
| Married filing jointly | $32,200 |
| Head of household | $24,150 |
Your taxable income is your gross income minus the standard deduction (or itemized deductions, if larger) and other adjustments. That’s the number the brackets apply to.
How marginal tax brackets actually work
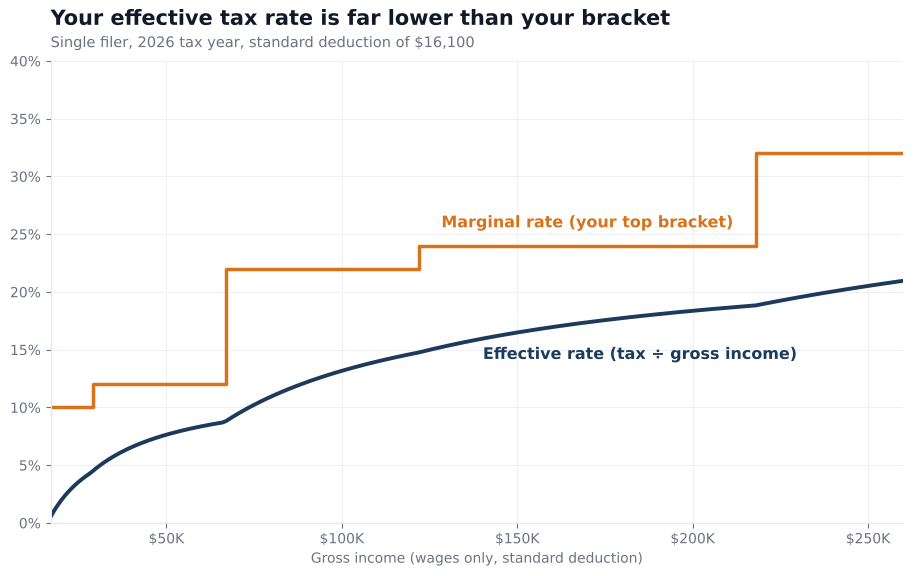
A common myth: “If I earn $1 over the bracket cutoff, all my income gets taxed at the higher rate.” Not true. Each slice of income is taxed at its own rate. Your marginal rate is the rate on your last dollar; your effective rate is total tax divided by total income – always lower.
Federal tax on $80,000 married filing jointly (2026 example)
Step 1 – Subtract the standard deduction: $80,000 − $32,200 = $47,800 taxable income.
Step 2 – Apply the brackets:
| Bracket | Income taxed in bracket | Tax |
|---|---|---|
| 10% | $24,800 | $2,480 |
| 12% | $23,000 | $2,760 |
| Total | $47,800 | $5,240 |
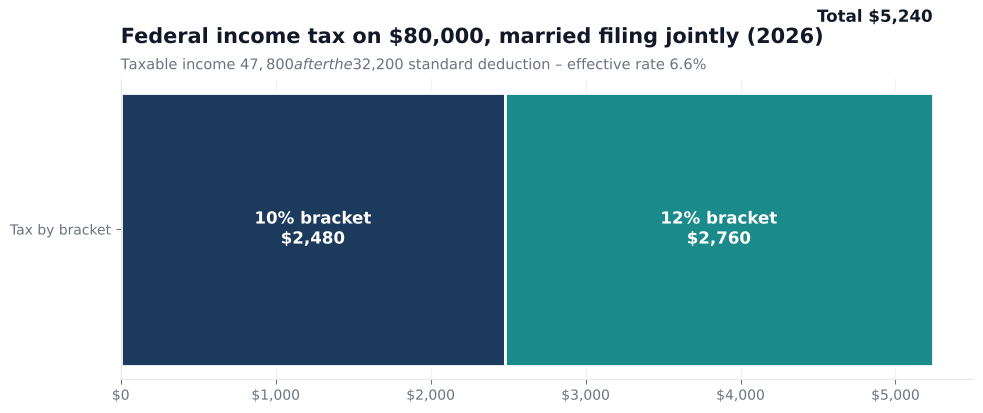
Total: $5,240, or 6.6% of gross income, even though the couple’s top bracket is 12%. Credits such as the child tax credit would reduce this further.
Estimated federal income tax at common incomes
Single filers
| Gross wages | Taxable income | Marginal rate | Federal income tax | Effective rate |
|---|---|---|---|---|
| $40,000 | $23,900 | 12% | $2,620 | 6.6% |
| $60,000 | $43,900 | 12% | $5,020 | 8.4% |
| $80,000 | $63,900 | 22% | $8,770 | 11.0% |
| $100,000 | $83,900 | 22% | $13,170 | 13.2% |
| $150,000 | $133,900 | 24% | $24,734 | 16.5% |
Married filing jointly
| Gross wages | Taxable income | Marginal rate | Federal income tax | Effective rate |
|---|---|---|---|---|
| $60,000 | $27,800 | 12% | $2,840 | 4.7% |
| $80,000 | $47,800 | 12% | $5,240 | 6.6% |
| $120,000 | $87,800 | 12% | $10,040 | 8.4% |
| $160,000 | $127,800 | 22% | $17,540 | 11.0% |
| $200,000 | $167,800 | 22% | $26,340 | 13.2% |
Assumes all income is wages, standard deduction only, no credits or other taxes. Rounded to the nearest dollar.
Head of household vs. single: what’s the difference?
If you’re unmarried and pay more than half the cost of keeping a home for a qualifying person, head of household status can lower your bill through a bigger standard deduction and wider low-rate brackets. Compare the same $80,000 income:
| Filing status | Standard deduction | Taxable income | Federal income tax | Effective rate |
|---|---|---|---|---|
| Single | $16,100 | $63,900 | $8,770 | 11.0% |
| Head of household | $24,150 | $55,850 | $6,348 | 7.9% |
| Married filing jointly | $32,200 | $47,800 | $5,240 | 6.6% |
Head of household saves about $2,422 versus filing single in this example. Eligibility rules are specific, so confirm with the IRS or a tax professional.
Why you get a refund (or owe)
Your bracket tax is the liability. Your refund or balance due depends on how much was withheld during the year. Withhold too much and you get a refund; too little and you owe. Estimate yours with our tax refund calculator. Freelancer or side hustler? Self-employment tax is a separate bill – use the self-employment tax calculator and read more at our tax and compliance hub.
5 ways to lower your federal income tax bill
- Contribute to a traditional 401(k) or IRA to reduce taxable income.
- Use an HSA if you’re eligible.
- Claim all credits you qualify for.
- Compare standard vs. itemized deductions.
- Adjust your W-4 so withholding matches your real tax.
Planning big purchases or a mortgage? Your tax picture affects what you can afford – see our home affordability calculator and debt-to-income ratio calculator.
Worked example: $60,000 single filer
To see the bracket math with three layers, here is a single filer with $60,000 of wages. Taxable income is $60,000 − $16,100 = $43,900:
| Bracket | Income taxed in bracket | Tax |
|---|---|---|
| 10% | $12,400 | $1,240 |
| 12% | $31,500 | $3,780 |
| Total | $43,900 | $5,020 |
Total federal income tax: $5,020, an effective rate of 8.4% even though the top bracket reached is 12%. Check your own numbers with the tax bracket calculator.
Will a raise push you into a higher bracket and cost you money?
No. A higher bracket only applies to the dollars above the threshold. Compare two $5,000 raises for a single filer:
| Raise of $5,000 | Extra federal tax | You keep | Tax on the raise |
|---|---|---|---|
| $60,000 → $65,000 (stays in 12% bracket) | $600 | $4,400 | 12% |
| $64,000 → $69,000 (crosses into 22% bracket) | $850 | $4,150 | 17.0% |
Even the raise that crosses into the 22% bracket leaves you with most of the money, because only part of it is taxed at the higher rate.
Deduction vs. credit: they are not the same
- A deduction lowers your taxable income. Its value depends on your bracket: a $1,000 deduction saves about $220 at a 22% marginal rate.
- A credit lowers your tax dollar for dollar: a $1,000 credit saves the full $1,000.
Standard vs. itemized deductions
You choose whichever is larger. A single filer with $80,000 of wages owes $8,770 using the $16,100 standard deduction. With $20,000 of itemized deductions instead, taxable income falls to $60,000 and the tax to $7,912 – a saving of $858. If your itemized deductions are below the standard deduction, take the standard one.
Federal income tax vs. payroll taxes (FICA)
The brackets above cover federal income tax only. Employees also pay Social Security and Medicare taxes at a combined 7.65% of wages (6.2% + 1.45%), subject to the Social Security wage limit. On $80,000 of wages that is about $6,120, so the couple in our example pays roughly $11,360 in federal income tax and employee payroll tax combined – about 14.2% of gross pay. Self-employed workers pay both halves, which you can estimate with the self-employment tax calculator.
How to estimate your 2026 federal income tax in 5 steps
- Add up your income: wages, interest, self-employment income and other taxable sources.
- Subtract adjustments: for example, traditional IRA contributions or student loan interest, if you qualify.
- Subtract the larger of the standard or itemized deduction to get taxable income.
- Apply the brackets layer by layer, as in the worked examples above.
- Subtract credits and compare to withholding to see whether you will owe or get a refund.
You can skip the manual steps by using the federal income tax calculator. Remember that quick estimates ignore many situations (investments, business income, phase-outs), so a tax professional or IRS.gov is the right place for final answers. Looking at the bigger picture of your finances? Our tax and compliance hub collects more tools.
6 common tax-bracket mistakes
- Believing your whole income is taxed at your top rate. It is not.
- Using gross income instead of taxable income. Subtract deductions first.
- Using last year’s brackets. The 2026 thresholds are higher than in prior years because of inflation adjustments.
- Ignoring credits. They can reduce tax far more than deductions.
- Forgetting payroll and state taxes. Your total tax burden is larger than the federal income tax alone.
- Not adjusting withholding. A big refund means you lent the government money interest-free; a big bill means you under-withheld.
Frequently asked questions
What are the 2026 federal tax brackets?
Seven rates: 10%, 12%, 22%, 24%, 32%, 35% and 37%. The top 37% rate starts above $640,600 for single filers and $768,700 for married couples filing jointly.
How much federal tax do I pay on $80,000?
Single: about $8,770. Head of household: about $6,348. Married filing jointly: about $5,240 – before credits.
Does a raise push me into a higher bracket and lower my pay?
No. Only the dollars above the bracket threshold are taxed at the higher rate.
Is the standard deduction the same as taxable income?
No. Subtract it from your income to find taxable income.
When do the 2026 brackets apply?
To income earned from January 1 to December 31, 2026, reported on the return you file in 2027.
Is the 2026 standard deduction higher than last year’s?
The 2026 amounts are $16,100 (single), $32,200 (married filing jointly) and $24,150 (head of household). They are adjusted annually for inflation and changed by recent tax law, so always confirm the current year on IRS.gov.
What is the difference between marginal and effective tax rate?
The marginal rate is the rate on your last dollar of taxable income; the effective rate is your total tax divided by your total income. The effective rate is always lower.
Do I pay tax on my whole refund?
No. A refund is a return of money you overpaid through withholding, not income. Estimate yours with the tax refund calculator.
- Tax Bracket Calculator – find your marginal and effective rate
- Federal Income Tax Calculator – estimate your 2026 bill
- Tax Refund Calculator – will you get money back?
- Self-Employment Tax Calculator – for freelancers
- Tax & Compliance Hub – more tax tools
- Home Affordability Calculator – what can you afford?
- Debt-to-Income Ratio Calculator – check your DTI
Sources & methodology
Brackets and standard deductions: IRS Revenue Procedure 2025-32 as summarized by the Tax Foundation. Tax computed progressively by bracket; examples exclude FICA, state/local taxes, credits and other deductions. Verify at IRS.gov. See how we calculate. This is general information, not tax advice.